- English
- Arabic
In This Blog Post
Share This Article
- Published: Nov 4, 2026
- Last Updated: Nov 4, 2026
- 🔊 Listen
TL;DR
- Financial resilience helps UAE businesses respond to uncertainty without relying only on cash reserves.
- Rolling cash flow forecasts can improve visibility over short-term funding needs and potential pressure points.
- Liquidity buffers should reflect revenue predictability, debt obligations, and access to committed funding.
- Currency, interest-rate, refinancing, and covenant risks need active monitoring across cross-border operations.
- Early-warning indicators can help finance teams identify emerging risks before they affect liquidity or operations.
- Connected financial systems improve visibility, but reliable decisions still depend on accurate underlying data.
- Strategic capital allocation should protect essential operations while preserving worthwhile growth investments.
Economic uncertainty is no longer a distant risk for UAE businesses. It is increasingly shaping everyday financial decisions, from when to pay suppliers and how much inventory to hold to whether the business can afford its next expansion.
The UAE’s position as a global trade, logistics, financial, and investment hub creates major opportunities, but it also exposes businesses to changes in regional trade, shipping costs, supply chains, financing conditions, and customer demand. According to the IMF’s October 2026 World Economic Outlook, UAE real GDP is projected to contract by 3.9% in 2026 before recovering by 7.7% in 2027.
For finance leaders, the message is clear: financial resilience depends on how well a business can anticipate, absorb, and respond to financial pressure through stronger cash flow, liquidity, working capital, and risk management.
Build Stronger Financial Visibility
Stay on top of cash flow, liquidity, and financial risk with expert support.
What does financial resilience mean?
Financial resilience is a business’s ability to withstand financial pressure, adapt to changing conditions, and continue operating without major disruption. It depends on strong cash flow, adequate liquidity, effective working capital management, risk controls, and the ability to make informed financial decisions when uncertainty increases. In the UAE, these capabilities are becoming increasingly important as businesses navigate into a more complex financial and operating environment.
Why is financial resilience becoming a strategic priority in the UAE?
The financial risks facing UAE businesses do not affect every industry equally. An international trading company may experience longer shipping routes and higher freight costs. A construction contractor may face delayed milestone payments while continuing to fund payroll and subcontractors. A hospitality operator may need to revise demand assumptions, while a professional services business may be more exposed to customer payment delays.
These differences matter because financial resilience cannot be built through a single liquidity policy.
Regional uncertainty is changing the risk landscape
The IMF’s October 2026 Regional Economic Outlook identifies disruptions to energy production and trade routes, rising food and energy costs, and heightened uncertainty across the Middle East.
Its assessment also recognises the adaptive capacity of regional economies, including firms’ efforts to reroute supply chains and manage disruption. This distinction is important. Economic pressure does not mean every UAE business is experiencing the same financial deterioration. Rather, businesses must examine their exposure to specific channels through which regional events can affect operating cash flow.
For CFOs, these channels include:
- Longer collection periods as customers manages their own liquidity
- Higher procurement, logistics, and insurance costs
- Reduced predictability of cross-border transactions
- Financing costs and refinancing risks
- Working capital tied up in inventory or delayed projects
- Changing customer demand and investment decisions
The priority is to determine which exposures could materially weaken the company’s liquidity position, rather than applying generalised assumptions about the regional economy.
UAE regulatory developments add another planning dimension
Businesses must also incorporate regulatory obligations into financial planning.
The UAE’s phased electronic invoicing implementation is a relevant example. Under the Ministry of Finance’s updated timetable, in-scope businesses with annual revenues of AED 50 million or more were required to appoint an Accredited Service Provider by 30 October 2026 and must now prepare to implement electronic invoicing by 1 January 2027.
For in-scope businesses below the AED 50 million threshold, the published implementation date is 1 July 2027, with an earlier service-provider appointment deadline.
These developments have implications beyond tax compliance.
Well-designed invoicing systems can potentially improve transaction visibility, reduce manual processing, and support more consistent receivables management. However, those improvements depend on successful integration with existing accounting and collection processes.
For finance leaders, regulatory readiness and operational efficiency should be considered together.
7 strategic pillars of financial resilience for UAE businesses
Building financial resilience requires coordination across financial planning, operations, treasury, and management reporting. The following seven-pillar framework gives UAE businesses a practical structure for improving cash visibility, managing financial risk, and making stronger decisions during periods of uncertainty.
-
Make cash flow forecasting dynamic rather than periodic
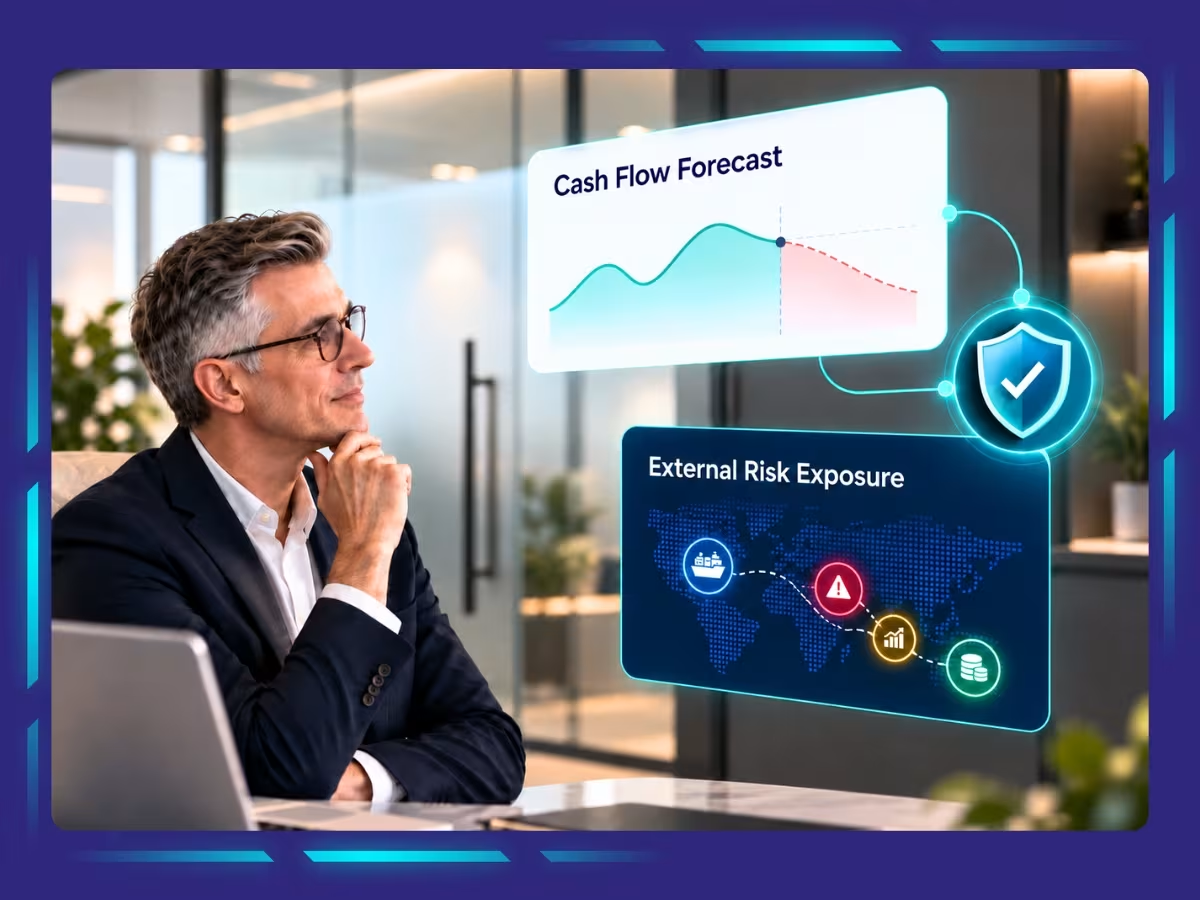
A rolling cash flow forecast helps businesses update expected receipts, payments, and funding needs continuously instead of relying on static monthly or quarterly forecasts. For UAE businesses with multiple customers, projects, or cross-border transactions, a 13-week direct cash flow forecast can provide stronger short-term visibility.
- Use rolling forecasts: Update expected inflows and outflows regularly as business conditions change
- Combine short- and long-term views: Support the 13-week forecast with longer-term projections for major commitments and investments
- Separate cash inflows by certainty: Distinguish between contracted receipts, expected collections, and less certain projected revenue
- Run downside scenarios: Model delayed customer payments, higher operating costs, or unexpected funding requirements
- Key KPI: Forecast accuracy, measured by the variance between projected and actual cash flows
- Watch the data quality: More frequent forecasting adds little value if operational assumptions and inputs are outdated
-
Manage working capital as a source of financial flexibility
Working capital determines how much cash is tied up between paying suppliers and collecting customers. For UAE businesses facing payment delays, fluctuating import costs, or inventory pressures, improving the cash conversion cycle can reduce dependence on external funding.
- Track the cash conversion cycle: Monitor DSO, inventory days, and payable days together rather than in isolation
- Segment receivables: Analyse customers by payment history, risk profile, and overdue period
- Review inventory commitments: Identify slow-moving or excess inventory without compromising operational continuity
- Assess supplier terms carefully: Negotiate payment terms where appropriate without automatically delaying supplier settlements
- Key KPI: Cash conversion cycle, supported by DSO and overdue receivables
- Balance liquidity with relationships: Aggressive collections or excessive inventory reductions may improve cash temporarily but damage customers, suppliers, or service continuity
-
Build liquidity buffers without freezing growth
Liquidity reserves provide protection when cash inflows weaken or unexpected obligations arise. The right buffer depends on revenue predictability, fixed commitments, debt obligations, and access to reliable external financing rather than a universal cash-reserve target.
- Use stress testing: Estimate liquidity needs under slower collections, revenue declines, or unexpected cost increases
- Review available liquidity: Consider unrestricted cash alongside committed financing facilities
- Track near-term obligations: Monitor debt maturities, payroll, supplier payments, and other unavoidable cash commitments
- Set liquidity thresholds: Define the minimum level of financial headroom management is willing to maintain
- Key KPI: Liquidity headroom, measured as available cash and committed funding above forecast cash requirements
- Avoid excessive conservatism: Holding too much idle cash may reduce risk, but delaying every worthwhile investment can weaken future competitiveness
-
Strengthen treasury, interest rate, and currency risk management
UAE businesses operating internationally may face exposure to currency movements, financing costs, and refinancing risk. Even though the UAE dirham is pegged to the US dollar, transactions involving other currencies can still create meaningful financial exposure.
- Map currency exposure: Compare the currencies in which revenue is earned with those used for expenses and liabilities
- Review interest-rate exposure: Identify variable-rate borrowing and assess the impact of changing financing costs
- Monitor refinancing concentration: Avoid excessive reliance on debt facilities maturing within the same period
- Track covenant requirements: Maintain visibility over financial conditions attached to loans and credit facilities
- Consider hedging selectively: Use hedging only where it addresses genuine commercial exposure rather than speculative currency expectations
- Key KPI: Net currency exposure by currency and the proportion of debt subject to variable interest rates
-
Establishfinancial early-warning indicators
Financial stress often appears in operational data before it becomes visible in headline profitability. Early-warning indicators can help finance leaders identify emerging risks in collections, liquidity, supplier dependence, debt, or cash flow before they become more difficult to manage.
- Monitor receivables: Track DSO and overdue customer balances
- Watch liquidity trends: Review cash conversion cycle, liquidity headroom, and forecast cash shortfalls
- Measure concentration risk: Monitor dependence on major customers and suppliers
- Track debt exposure: Review upcoming maturities and covenant headroom
- Compare cash with earnings: Monitor operating cash flow relative to EBITDA
- Key KPI: Percentage of financial risk indicators exceeding internally approved thresholds
- Create accountability: Every indicator should have a defined owner, escalation threshold, and management response
-
Connect financial systems to decision-making
Financial technology strengthens resilience when it improves the speed, consistency, and usefulness of financial information. For multi-entity UAE businesses, integrating accounting, receivables, payables, and treasury data can provide management with a clearer consolidated financial view.
- Integrate financial systems: Connect accounting, AP, AR, treasury, and reporting data where possible
- Automate repetitive processes: Use automation for invoice processing, reconciliation, and routine financial reporting
- Use dashboards for visibility: Present cash flow, working capital, and liquidity trends in a form management can act on quickly
- Improve consolidation: Reduce delays caused by disconnected entities, spreadsheets, or reporting systems
- Key KPI: Time required to produce a reconciled and consolidated cash position
- Protect data quality: Automation and dashboards are only reliable when the underlying accounting records, controls, and ownership are strong
-
Protect strategic capital allocation
Financial resilience should help businesses make better investment decisions, not simply reduce spending. During periods of uncertainty, finance leaders need to distinguish between discretionary expenditure and investments that protect operations, improve efficiency, or support long-term growth.
- Prioritise essential investments: Protect projects that support critical operations or business continuity
- Assess working-capital benefits: Continue investments that materially improve cash conversion or operating efficiency
- Evaluate risk-adjusted returns: Compare potential returns with financial risk and liquidity impact
- Use scenario analysis: Test planned investments under different revenue, cost, and cash flow conditions
- Avoid blanket spending cuts: Not every investment should be postponed simply because uncertainty has increased
- Key KPI: Risk-adjusted investment returns and liquidity headroom after planned capital commitments
Financial resilience is ultimately about better financial decisions
For UAE businesses, financial resilience is not about eliminating uncertainty. It is about building the visibility, liquidity, controls, and decision-making discipline needed to respond when conditions change. Stronger cash flow forecasting, working capital management, liquidity planning, risk monitoring, connected financial systems, and disciplined capital allocation can help finance leaders identify pressure earlier, protect critical operations, and continue investing in opportunities that support long-term growth.
At Whiz Consulting, we help UAE businesses strengthen financial resilience through structured accounting and finance support. Our team assists with bookkeeping, accounts payable and receivable, cash flow reporting, reconciliations, management reporting, budgeting, forecasting, and financial analysis. By combining accurate financial records with timely reporting and expert review, our accounting outsourcing services help businesses improve financial visibility, monitor risks more closely, and make better-informed decisions across changing economic conditions.
Disclaimer:
Principal Research References
- IMF, World Economic Outlook, October 2026. UAE GDP projections and regional economic context.
- IMF, Regional Economic Outlook: Middle East and Central Asia, 22 October 2026. Regional disruptions, adaptation and risk outlook.
- Central Bank of the UAE, Publications. Quarterly economic reviews, credit sentiment and financial stability research.
- UAE Ministry of Finance, eInvoicing Update, 10 May 2026. Amended service-provider appointment deadline.
- UAE Ministry of Finance, eInvoicing Update, 27 September 2026. Implementation readiness and regulatory deadlines.

Get customized plan that supports your growth
Have questions in mind? Find answers here...
There is no single risk common to every business. Liquidity pressure can emerge from delayed receivables, supply chain disruption, rising operating costs, financing constraints, or concentrated customer exposure. The greatest risk is often the interaction of several pressures that the business has not adequately anticipated.
There is no universal reserve requirement suitable for every business. The appropriate amount depends on operating costs, revenue predictability, debt obligations, financing access, and scenario-based cash requirements. Businesses should establish internal liquidity targets through financial stress testing rather than relying on a fixed rule of thumb.
A weekly review of a rolling 13-week cash flow forecast is a useful starting point for many businesses. Organizations facing more immediate liquidity pressure may require daily monitoring, while longer-term financial planning should incorporate monthly or quarterly scenarios.
Yes. Timely reconciliations, reliable receivables and payables records, and accurate management reporting improve visibility into financial obligations and cash movements. However, accounting accuracy must be combined with forecasting, risk assessment, and management action to strengthen financial resilience.
SMEs may have fewer financing options and less specialized treasury capacity. Their priorities often include cash collection, reliable short-term forecasting, and avoiding excessive customer concentration. Larger enterprises typically need consolidated visibility across entities, currencies, borrowing arrangements, and complex commercial commitments.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.